From the Pentagon to defense manufacturers, logistics companies, and reconstruction contractors — tracing the corporations behind twenty-five years of American military spending.
By Patrick Panteix | WAR: FOLLOW THE MONEY
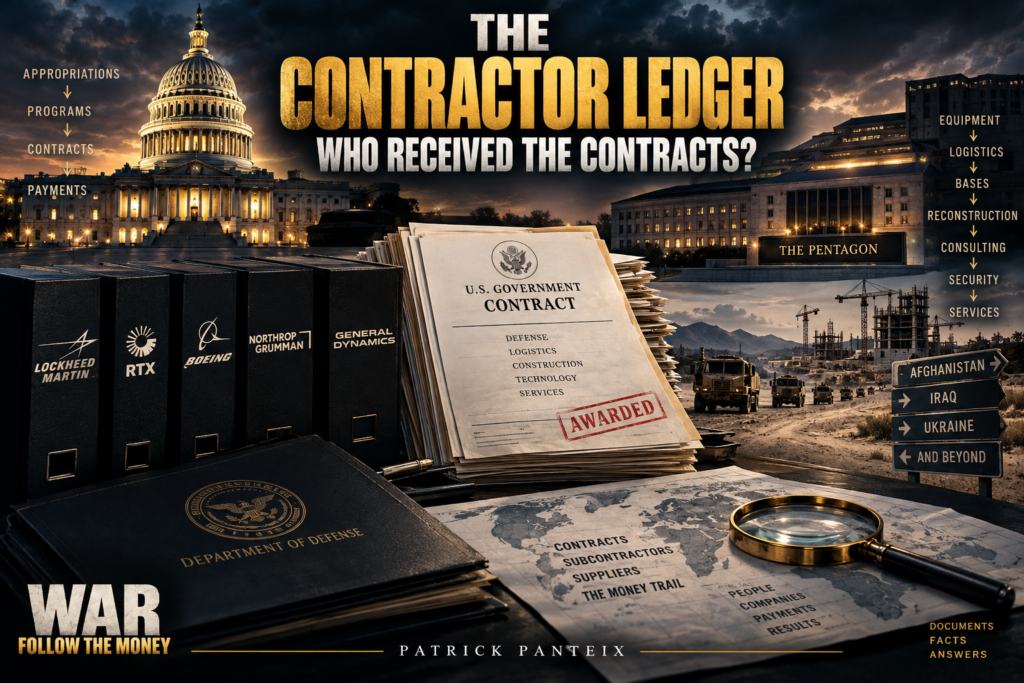
The Names Behind the Numbers
When Congress appropriates money for military operations, the funds do not travel directly from Washington to the battlefield.
They pass through federal departments, procurement programs, contractual commitments, and payment systems.
Along the way, private companies become responsible for supplying equipment, maintaining military systems, transporting personnel and materials, constructing facilities, providing technical services, and supporting military operations.
Some manufacture aircraft, missiles, and armored vehicles.
Others provide fuel, logistics, communications equipment, information technology, construction, or specialized services.
Their names appear throughout the federal government's procurement records.
But identifying a contractor is only the beginning of the investigation.
The questions that follow are more demanding.
How much federal money was committed to the company? What was the government purchasing? How much was actually paid? Which subcontractors participated? And what can the available financial records establish about the money ultimately received?
These questions form the basis of the contractor investigation in WAR: FOLLOW THE MONEY.
The objective is to reconstruct the financial relationships between the American government and the companies that supplied goods and services during twenty-five years of warfare.
The starting point is the federal contract record.
1. Five Companies and $132.9 Billion in Contract Obligations
The scale of the American defense contracting system can be illustrated through the Department of Defense's procurement data.
According to a Congressional Research Service report updated on February 6, 2026, the Department of Defense recorded approximately $445.1 billion in contract obligations during fiscal year 2024.
Five companies accounted for approximately 30% of that amount.
The figures published by the Congressional Research Service were:
Defense contractor FY2024 contract obligations
Lockheed Martin Corporation $50.7 billion
RTX Corporation $24.8 billion
The Boeing Company $23.2 billion
Northrop Grumman Corporation $18.6 billion
General Dynamics Corporation $15.6 billion
Combined total $132.9 billion
Source: Congressional Research Service, Defense Primer: Department of Defense Contractors, updated February 6, 2026. Figures represent Department of Defense contract obligations in fiscal year 2024, not payments received or corporate profits.
These figures establish the scale of the federal contracting relationships involving these corporations during one fiscal year.
They do not establish that $132.9 billion was spent on warfare.
The Department of Defense finances a broad range of activities, including military readiness, equipment procurement, research, maintenance, and other operations.
A contract awarded during fiscal year 2024 may support a program unrelated to a particular war. It may also finance equipment or services used over several years.
Consequently, annual defense contracting figures cannot automatically be presented as the cost of Afghanistan, Iraq, Ukraine, or any other individual conflict.
They provide a starting point for identifying major federal contractors.
Determining which transactions relate to a specific war requires examining the underlying contracts, programs, and purposes.
2. Iraq and Afghanistan: $159 Billion in Documented Contract Obligations
The financial record becomes more specific when the investigation focuses on Iraq and Afghanistan.
In a report published in September 2012, the Government Accountability Office examined contracting activities associated with these two countries.
According to the GAO, the Department of Defense, Department of State, and U.S. Agency for International Development reported approximately $159 billion in combined contract obligations between fiscal years 2002 and 2011.
The figure covered contracts whose principal place of performance was Iraq or Afghanistan.
This distinction is essential.
The $159 billion figure was not a complete estimate of American war spending during those years.
It covered a defined category of contracts, reported by three federal agencies, over a specific period.
It did not include every military expenditure associated with the two conflicts.
Nor did it represent a comprehensive accounting of all contracts performed elsewhere in support of military operations.
Nevertheless, the amount illustrates the substantial financial role contractors played in supporting American operations.
Companies were engaged to deliver goods and services ranging from construction and transportation to security, logistical support, and reconstruction activities.
The contractor network extended well beyond the manufacturers traditionally associated with military equipment.
Understanding the financial architecture of these wars therefore requires examining both defense manufacturers and the companies supplying the services necessary to sustain military operations.
It also requires identifying the difference between a company's role as a federal contractor and its eventual financial results.
A contract obligation is a government commitment.
It is not automatically an amount paid to the contractor.
And it is certainly not equivalent to the contractor's profit.
3. The Prime Contractor Is Not Always the Final Recipient
Federal procurement records often identify the prime contractor: the company or organization that maintains the direct contractual relationship with the government.
But major contracts may involve additional businesses.
A company awarded a contract to manufacture military equipment may purchase components from specialized suppliers.
A logistics contractor may employ transportation companies, maintenance providers, and other subcontractors.
A construction project may involve engineering firms, material suppliers, and local businesses.
The federal government's USAspending.gov database distinguishes between prime awards and subawards, which are agreements made by prime recipients with other organizations to carry out part of the funded work.
For an investigator following the money, this creates several levels of analysis.
The first identifies the government agency awarding the contract.
The second identifies the prime contractor receiving the award.
The third examines subcontractors and other downstream recipients where records are available.
The fourth seeks to establish the economic destination of the funds through payment records, financial disclosures, and other documentation.
These levels cannot always be reconstructed with the same degree of precision.
In a 2014 report, the GAO examined federal subcontracting information and identified limitations in the ability of government reporting systems to link subcontractors with the corresponding prime contracts.
Its analysis showed that different systems contained different levels of information about subcontractors, subcontracting plans, and lower-tier contractual relationships.
The public record therefore does not always provide a complete picture of every company participating in a major federal contract.
That limitation matters when attempting to determine where the money ultimately went.
Identifying the prime contractor establishes an important financial relationship. It does not necessarily identify every business that subsequently received a portion of the funds.
4. A Contract Award Is Not Corporate Profit
One of the most important distinctions in the investigation concerns the relationship between government contracts and corporate financial performance.
Consider a hypothetical example.
The Pentagon awards a company a contract with an initial value of $1 billion.
The company subsequently purchases materials, pays employees, contracts with suppliers, finances production, and delivers the goods or services required under the agreement.
The government may make payments over several years, depending on the contractual terms and the performance of the work.
The company's financial statements may recognize revenue as contractual obligations are fulfilled under the applicable accounting rules.
But the original contract value does not establish the amount of profit generated.
Costs must be considered.
Payments must be distinguished from obligations.
And revenue must be distinguished from net income.
If the company performs several different contracts, its consolidated financial statements may not separately disclose the profit attributable to each individual military program.
For WAR: FOLLOW THE MONEY, these distinctions determine how the financial evidence is presented.
A federal contract award can establish the existence and reported value of a contractual relationship.
Government payment records can provide information about amounts actually disbursed.
Corporate filings can establish reported revenue and financial performance within their disclosed accounting categories.
But those figures cannot simply be substituted for one another.
CONTRACT OBLIGATIONS ≠ PAYMENTS ≠ CORPORATE REVENUE ≠ PROFIT.
The objective is to establish what each financial record actually measures before drawing conclusions from it.
5. The Cost of Contracting Does Not End When a Contract Is Awarded
A contract award marks the beginning of a contractual commitment, not necessarily the completion of the government's financial obligations.
The contractor must perform the agreed work.
The government must assess whether the required goods or services have been delivered.
Payments must be reconciled.
And the contract must eventually be closed.
These processes can continue long after the military operation that originally required the contract has ended.
In September 2011, the GAO reported that the Department of Defense had obligated at least $166.6 billion on contracts supporting reconstruction and stabilization efforts in Iraq and Afghanistan since 2002.
The agency examined problems associated with closing contingency contracts, including the need to reconcile financial obligations and determine whether unspent funds could be recovered or used for other purposes.
The $166.6 billion figure came from a different reporting scope than the $159 billion discussed earlier.
The figures must not be added together.
They describe overlapping contracting activity through different measures and reporting periods.
Their significance lies in what the reports reveal about contract administration.
A military operation can end while the government continues to resolve its contractual and financial commitments.
Outstanding obligations, final payments, contract reconciliation, and unresolved administrative matters can extend beyond the period of active combat.
This means that examining wartime contracting requires more than identifying the largest awards announced during the conflict.
It also requires studying the financial consequences that remain after the contracts have been performed.
6. What the Public Record Can—and Cannot—Tell Us
The federal government maintains extensive procurement databases.
These records make it possible to examine contracting activity by agency, recipient, program, location, and financial measure.
But public procurement information has limitations.
In a September 2025 report, the Government Accountability Office examined the quality of information reported to the Federal Procurement Data System, which supplies procurement data displayed on USAspending.gov.
The GAO identified weaknesses in procurement data quality procedures and reporting practices.
Its findings illustrate why investigators must assess the reliability and completeness of federal records rather than assuming that every published dataset provides a complete financial picture.
The same principle applies to subcontracting information.
A federal database may identify the company that received the initial award without providing a complete account of subsequent payments throughout the supply chain.
Corporate financial statements may disclose revenue by business segment without establishing the exact profitability of an individual federal contract.
A government audit may identify weaknesses in contract oversight without establishing that the entire value of the contract was wasted or improperly paid.
These distinctions are not merely technical details.
They determine what can legitimately be concluded from the evidence.
A documented contract establishes a contractual relationship.
A documented payment establishes that money was disbursed.
A documented audit finding establishes the specific condition identified by the auditor.
But none of those facts should be expanded into a broader allegation without additional evidence.
The investigation must distinguish what the records demonstrate from what remains unknown.
7. The Contractor Ledger: Following the Financial Record
Twenty-five years of American warfare generated financial relationships involving government agencies, defense manufacturers, logistics providers, construction companies, reconstruction contractors, consultants, and numerous other organizations.
Understanding those relationships requires examining the financial record at several levels.
The investigation begins with the government agency responsible for the expenditure.
It identifies the relevant contract and the company awarded the work.
It examines the contractual purpose, the reported obligations, the available payment information, and the participation of subcontractors where that information can be established.
It then considers the company's financial disclosures and the findings of government oversight bodies.
The resulting record provides a way to distinguish documented recipients from assumed beneficiaries.
It also makes it possible to identify the limits of the available evidence without treating every gap in public reporting as proof of wrongdoing.
That is the purpose of the contractor investigation in WAR: FOLLOW THE MONEY.
The book follows the financial relationships connecting American military expenditure to the organizations that supplied goods and services throughout the conflicts examined.
Not every contract was a weapons contract.
Not every dollar was spent overseas.
Not every dollar obligated was immediately paid.
And not every payment received by a contractor became corporate profit.
The public record provides many of the pieces needed to reconstruct these financial relationships.
The challenge is connecting them without counting the same money twice or claiming that the documents establish more than they actually do.
The question is not simply which companies received the largest contracts.
It is what those contracts purchased, how much public money was committed and paid, who appears in the documented chain of transactions, and where the financial trail can still be followed.
That is where the contractor ledger begins.
ABOUT THE BOOK
WAR: FOLLOW THE MONEY
Where the Money Goes Before, During, and Long After the Fighting Ends
Patrick Panteix's investigative nonfiction project examines the financial record of twenty-five years of American warfare, from 2001 to 2026.
Drawing on congressional records, government audits, federal contract databases, corporate filings, and official budget documents, the book follows the financial relationships connecting public spending, military operations, private companies, and long-term obligations.
The project is currently in development, and literary representation is being sought.
Patrick Panteix — Investigative Nonfiction Author
SOURCES AND RESEARCH DOCUMENTATION
[1] Congressional Research Service — Defense Primer: Department of Defense Contractors (IF10600).
Department of Defense contract obligations, major federal contractors, and the distinction between prime contractors and subcontractors.
Read the Congressional Research Service report
[2] U.S. Government Accountability Office — Contingency Contracting: Agency Actions to Address Recommendations by the Commission on Wartime Contracting in Iraq and Afghanistan (GAO-12-854R).
September 2012. Federal contracting in Iraq and Afghanistan, including approximately $159 billion in reported obligations between fiscal years 2002 and 2011.
[3] USAspending.gov — Federal Spending Guide.
Official guidance explaining federal contract awards, prime recipients, subawards, and the classification of federal spending data.
Read the Federal Spending Guide
[4] U.S. Government Accountability Office — Federal Subcontracting: Linking Small Business Subcontractors to Prime Contracts Is Not Feasible Using Current Systems (GAO-15-116).
December 2014. Examination of federal subcontracting information and the limitations of government reporting systems.
[5] U.S. Government Accountability Office — Contingency Contracting: Improved Planning and Management Oversight Needed to Address Challenges with Closing Contracts (GAO-11-891).
September 2011. Examination of contract administration and financial risks associated with closing contracts supporting operations in Iraq and Afghanistan.
[6] U.S. Government Accountability Office — Federal Spending Transparency: Actions Needed to Help Ensure Procurement Data Quality (GAO-25-107469).
September 2025. Examination of federal procurement reporting and the reliability of data submitted to government contracting systems.